
Tax Lab
Tax-smart distribution planning at your fingertips
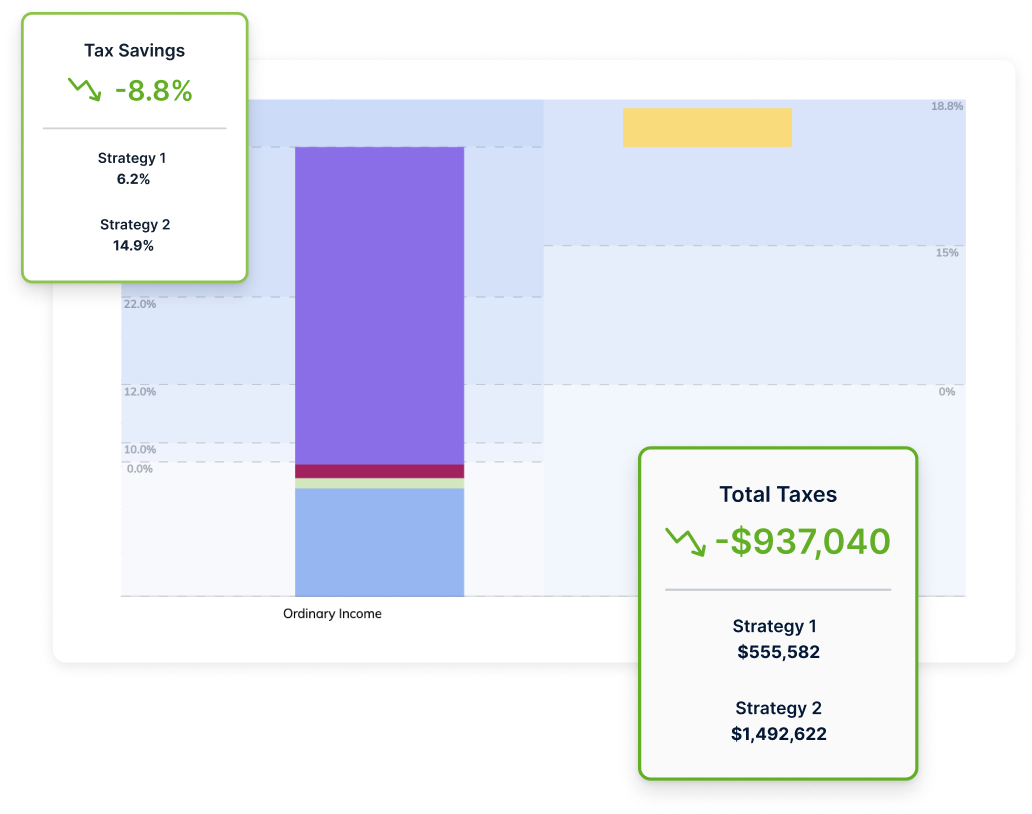

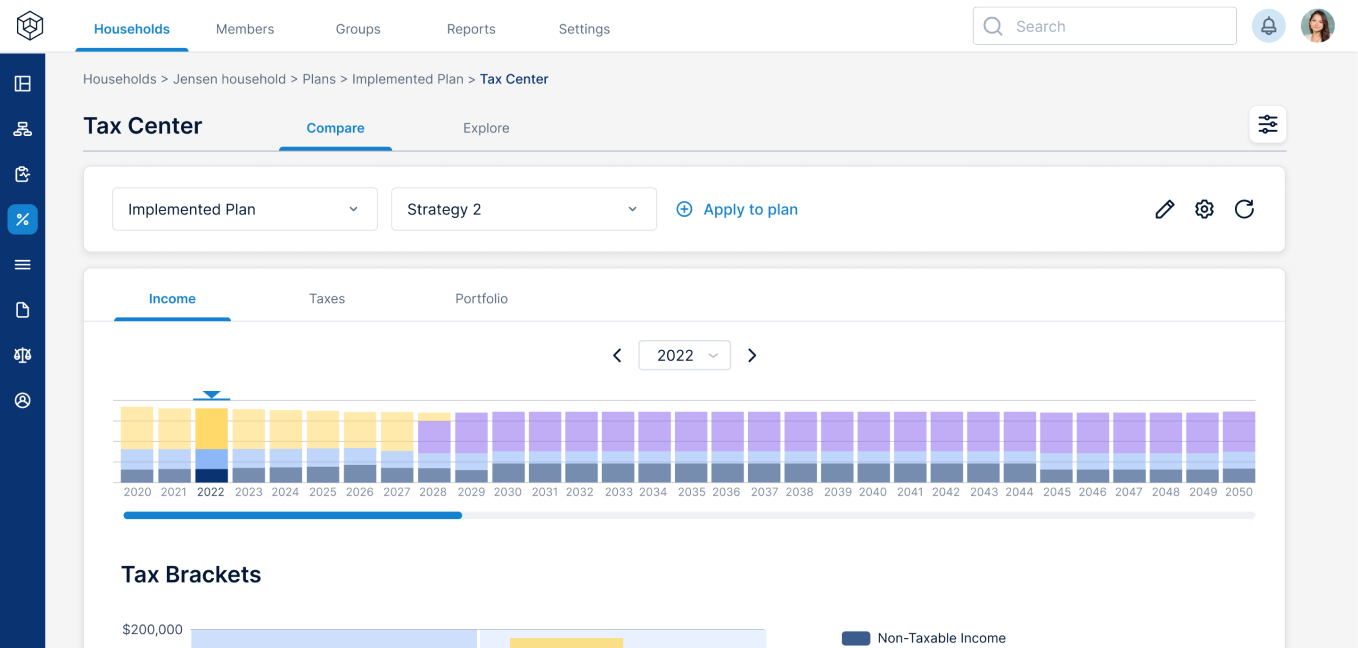
Once you know how much a client can spend, the next questions are, “where should we take distributions from, down to the account level” and “should we consider Roth conversions?”. Income Lab’s Tax Lab helps you answer these questions quickly and estimate the full value of tax-smart distribution planning. Tax Lab runs distribution strategies in parallel on the client's own plan, holding everything else constant, and compares them side by side on total taxes, net income and net legacy. It stars the strategy with the highest projected net income, so the conversation starts from a ranked comparison.
In a recent survey by Herbers & Company, 90% of investors want tax planning assistance.

"Income Lab is the most comprehensive and sophisticated retirement income solution in the current fintech landscape. Not only does it facilitate better, more informed decisions about retirement distribution sufficiency; it also models the various decumulation strategies on an after-tax basis, to help advisors help clients maximize their after-tax retirement income."
Bob Veres
Inside InformationDeciding how best to source portfolio withdrawals involves accounting for a full range of tax effects and a wide range of withdrawal strategies as they apply to each plan. Income Lab helps you quickly evaluate the tax consequences of strategies like Roth conversions, including the complex interactions of different types of income and their differential tax treatment, and produces simple, digestible data to help you and your clients make informed decisions.
Income Lab is comprehensive financial planning software for financial advisors, with tax planning built into the client's plan. IRMAA, federal tax, state tax and Social Security taxation interact, and solving one in isolation can cost the client in another. Tax Lab runs inside the same plan as the client's income, Social Security and spending guardrails, so its results reflect what the plan already knows.
Bracket management strategies use Roth conversions to fill a target federal bracket, with the conversion years, an annual cap and a floor on tax-deferred balances set by you. IRMAA bracket strategies target a Medicare premium tier, applying the two-year lookback from the fourth plan year; the first three plan years use current-year MAGI. Withdrawal strategies include a tax-ordered draw: taxable, then tax-deferred, then tax-free. Tax Lab models state income tax for all 50 states and DC, next to federal tax, capital gains and IRMAA. Add a local rate where one applies.
Tax Lab is included in Income Lab Core at $199/month. Pro, at $299/month, adds Penny's tax tools: upload a 1040 to Penny for a tax summary in seconds; use the IRMAA appeal calculator to estimate the surcharge savings and generate instructions for Form SSA-44, the life-changing-event request the client files with Social Security; and use Withdrawal Optimizer to see which accounts should fund a one-time withdrawal, what it costs in tax, and where it sits against bracket and Medicare lines. Compare Core and Pro.
Tax figures in Income Lab are estimates based on plan inputs and are not tax or legal advice. Strategy rankings are projections, not guarantees.
How to size conversions, manage bracket thresholds, and use Tax Lab to model multi-year strategies.
Navigate Medicare surcharge cliffs and coordinate IRMAA planning with Roth conversion timing.
OBBBA bracket changes, SALT cap updates, and how the new senior deduction affects conversion strategy.
State-level tax treatment of retirement income, Social Security, and how relocation changes the plan.
Which accounts should fund a client's one-time withdrawal, and the estimated tax cost against the current-year plan.